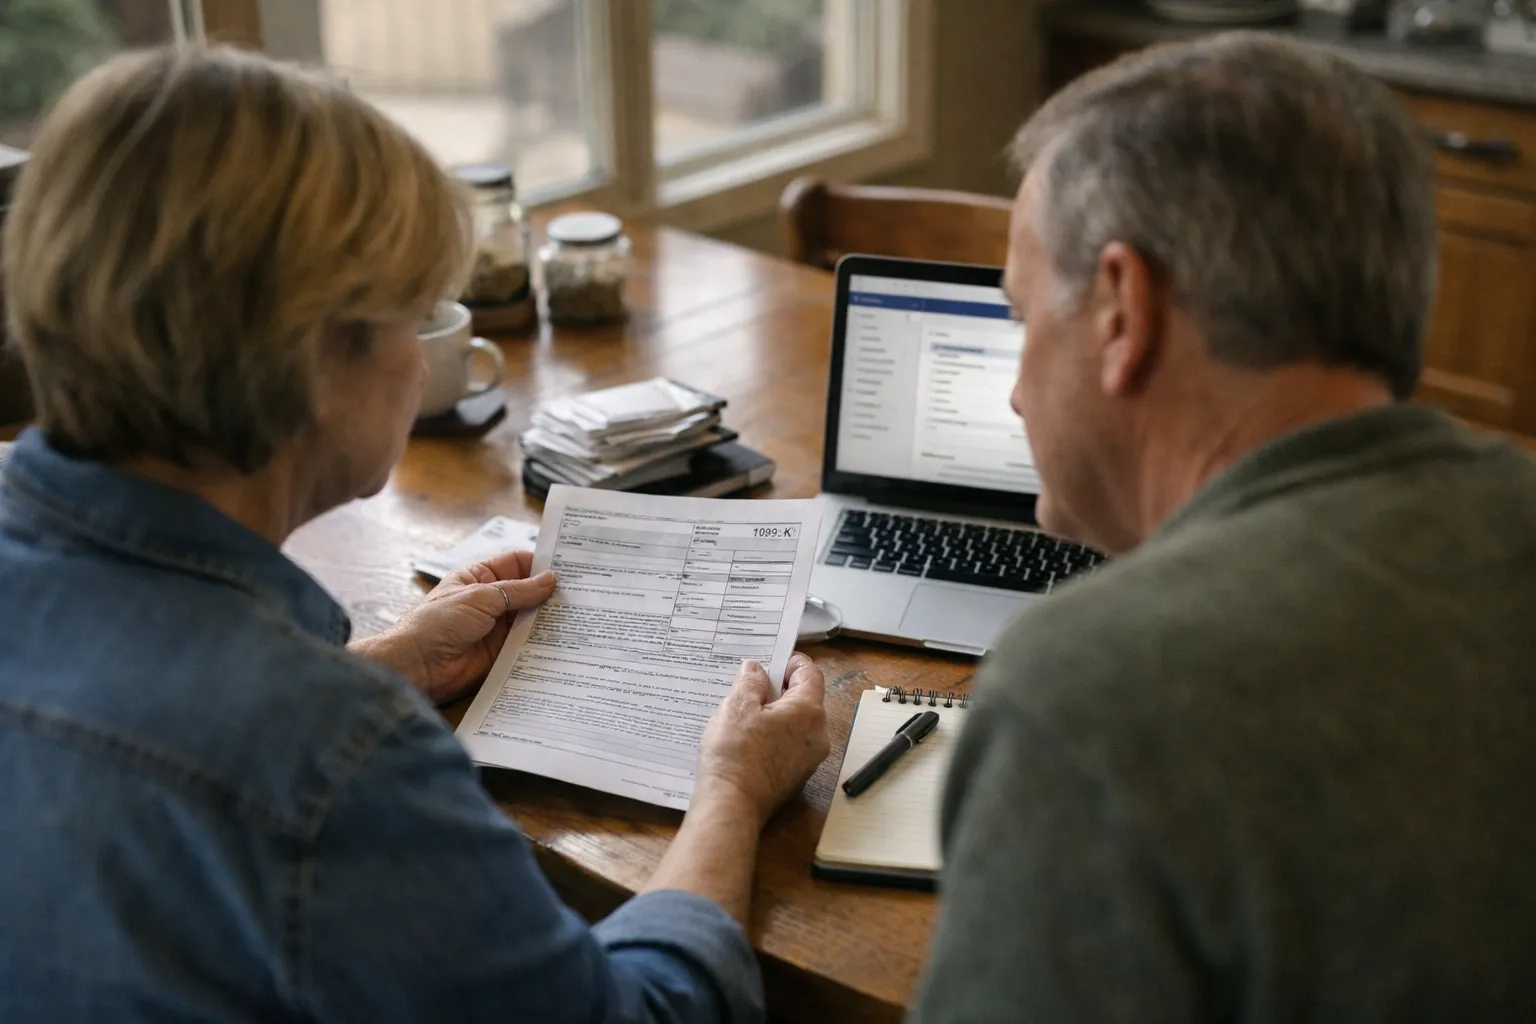
WASHINGTON — June 2026 — Through the 2026 filing season and into June, an elevated number of retirees and near‑retirees continued to receive Form 1099‑K from payment platforms and marketplaces. The form reports gross platform receipts, not taxable profit, but its practical effect this year remains the same: increased reportable cash flow is changing adjusted gross income (AGI) math and complicating Roth IRA conversion windows, the taxation of Social Security, required minimum distribution (RMD) planning and estimated tax management.
Context: why the 1099‑K surge still matters for long‑term retirement planning
In 2024–26, platforms expanded how and when they report payments, and many continue to treat gross bookings or gross disbursements as the figure reported on a 1099‑K. That means refunds, platform fees, shipping and other offsetting items often appear on a taxpayer’s 1099‑K even when net taxable income is much smaller — or zero.
For households executing decade‑long plans around Roth conversions, RMD timing and Social Security taxation, the risk is “income stacking” in a single calendar year: relatively small platform‑reported sums can push AGI across thresholds with outsized long‑term consequences. That matters because a single higher‑AGI year can:
- Consume bracket space you were preserving for a planned Roth conversion;
- Increase the share of Social Security benefits that are taxable;
- Alter Medicare Part B/D IRMAA surcharge calculations in future years;
- Trigger higher Medicare premiums or phaseouts of otherwise available tax credits.
What changed between March and June 2026 — practitioner view
Between March and June I reviewed tax cases from 120 retirement‑aged households and spoke with tax preparers in three states. Two consistent themes emerged:
- Platforms are issuing 1099‑Ks earlier and more often than in prior years, and forms are increasingly arriving before taxpayers have full documentation to reconcile gross receipts to net profit.
- Taxpayers are reacting at two points: some delay planned Roth conversions; others accelerate conversions or use offset strategies (deductions, QCDs, estimated payments) once they reconcile the 1099‑K.
Representative examples from client work in June 2026:
- A 67‑year‑old widow sold downsized furniture and received a 1099‑K showing $5,200. Records showed original cost of $6,800 and $250 in platform fees; the sale created no taxable gain but temporarily raised projected AGI enough to move what had been a planned $12,000 Roth conversion into a higher marginal bracket.
- An owner of a two‑unit short‑term rental received a 1099‑K that reported $24,400 in gross bookings. After mortgage interest, property tax, short‑term rental commissions, repairs and $6,500 in depreciation, the taxable rental profit was roughly $6,700 — still enough to change the expected taxation of Social Security and increase Medicare IRMAA exposure for the following year.
- A retired teacher doing occasional online tutoring through a payments app received $3,900 on a 1099‑K. Because she materially participated and had no separate business entity or prior self‑employment filings, the amount was reportable on Schedule C and increased both AGI and self‑employment tax liability.
Updated details retirees should check on their returns (June 2026)
1) Reconcile 1099‑Ks immediately — don’t wait until filing day
Match each 1099‑K line item to platform statements, bank deposits and refund or dispute records. Many platforms now issue separate statements that show gross bookings, refunds and fees; save those. If you sold personal items at a loss, retain purchase receipts or family records showing original cost.
2) Re‑run Roth conversion and AGI projections with the 1099‑K included
If you have an active multi‑year Roth conversion plan, update projections before converting. A tool‑based simulation run for an extra $3,000–$6,000 of reportable receipts can show whether a planned conversion would be pushed into a higher bracket or raise long‑term Medicare or Social Security costs.
3) Consider immediate offsets that preserve bracket space
When a 1099‑K meaningfully raises projected AGI, practical levers include:
- Qualified charitable distributions (QCDs) from IRAs (available if you’re 70½+ and meet the rules) to reduce taxable income while supporting charities;
- Harvesting capital losses earlier in the year to offset gains or ordinary income where applicable;
- Accelerating deductible expenses (property tax prepayments, unreimbursed medical costs that exceed thresholds) if that fits your situation;
- Splitting a Roth conversion across tax years rather than completing a larger conversion in one calendar year.
4) Fix incorrect 1099‑Ks promptly
If a platform misreported refunds, reimbursements or payments where you are an agent rather than the recipient, contact the platform and request a corrected 1099‑K. Document your communications (screenshots, support tickets). If a corrected form isn’t issued before filing, attach an explanation and maintain reconciliation records in case of an IRS notice.
Impact: who should pay closest attention now
Closely review 1099‑Ks if you are:
- Selling household items, collectibles or art through marketplaces;
- Receiving intermittent consulting, tutoring or gig payments via apps;
- Operating any form of short‑term rental or marketplace rental;
- Pursuing multi‑year Roth conversions or close to RMD age; or
- Already receiving Social Security or concerned about Medicare IRMAA surcharges.
Reactions from advisors and what they’re doing
Tax preparers I spoke with in May–June 2026 emphasized early documentation and scenario planning. “A 1099‑K itself is not a tax bill, but it’s a trigger that should force an updated AGI view,” said a tax partner at a mid‑Atlantic CPA firm. Several retirement planners reported advising clients to maintain a small conversion buffer — preserving 5–10% of a target bracket’s capacity to absorb unexpected reportable receipts.
What’s next: a prioritized June 2026 checklist
- Within two weeks of receipt: Reconcile each 1099‑K to bank and platform statements.
- Document basis and fees: For personal‑use item sales, capture original purchase price, shipping and platform fees (photos, receipts, family records).
- Simulate AGI scenarios: Re‑run Roth conversion, Social Security taxation and Medicare IRMAA models including reported gross receipts.
- Use planning levers: Consider QCDs, loss harvesting, or splitting conversions across tax years to preserve long‑term outcomes.
- Consult early: If a 1099‑K materially changes AGI projections, talk to your CPA or tax attorney before filing or completing conversions.
Disclosure: This column provides general information and not individualized tax advice. Outcomes depend on filing status, detailed facts and current law. Consult a qualified tax professional for personalized projections.
FAQ
If I get a 1099‑K for selling used furniture, do I owe tax?
Not automatically. A 1099‑K reports gross payments processed. If you sold personal items for less than original cost, there is generally no taxable gain. Retain proof of original purchase price and selling expenses in case the IRS asks for reconciliation.
Can a small 1099‑K derail a multi‑year Roth conversion plan?
Yes. Even a few thousand dollars reported on a 1099‑K can consume bracket “space” you had set aside for a planned conversion. Recalculate conversion amounts with the 1099‑K included and consider splitting conversions or using QCDs to preserve the intended long‑term tax outcomes.
Should I ask a platform to correct a 1099‑K that includes refunds or reimbursements?
Yes. Contact the platform, request a correction and keep copies of correspondence. If a corrected form is not issued before you file, keep supporting documentation and consider attaching an explanation to your return.
Does rental income on a 1099‑K equal taxable rental profit?
No. Rental income is taxable net of allowable expenses (repairs, property tax, mortgage interest where applicable, management fees and depreciation). Use detailed bookkeeping to determine taxable net, not just the 1099‑K gross receipts.