By David Park — Real Estate & Tax Correspondent
Overview: What we’re analyzing and why it matters
Deciding between a pension lump sum and a lifetime annuity remains one of the single biggest levers shaping retirees’ financial security and legacy. As of August 2026 the trade-off is still the same—trade certainty for flexibility—but the context has shifted. Higher long-term yields compared with the 2010s, broader in-plan guaranteed-income options, and evolving annuity product designs mean the effective price of guaranteed income is different today. Equally important: tax timing (RMDs at 73 under SECURE Act 2.0), Medicare surcharges, and multigenerational goals now interact with annuity choice in more complex ways. This update gives practical, current guidance to help you make a market-tested, tax-aware decision that aligns with multigenerational goals.
Background: What’s changed through August 2026
Three developments since early 2026 are especially relevant:
- Yields and annuity pricing: Fixed-income yields have remained elevated relative to the 2010s low-rate era. That has kept single-premium immediate annuity (SPIA) payouts materially higher than they were in 2020–2021, narrowing the historical performance gap between guaranteed lifetime income and conservative portfolio withdrawals.
- In-plan guaranteed income and portability: More defined-contribution plans now offer in-plan guaranteed-income windows or portability to pre‑negotiated insurer partners. This reduces friction for participants who prefer to annuitize a portion of their plan without a full lump-sum cash-out.
- Product innovation and competition: Insurers and insurtech marketplaces have expanded options—joint-and-survivor guarantees with flexible payout start dates, limited-COLA riders, and deferred income annuities (DIAs) designed to start at advanced ages (80–85) as a longevity backstop.
Data and evidence: the facts to anchor a decision
Retirees should anchor their analysis in three verifiable, real‑time data points:
- Current SPIA quotes: Obtain same-day quotes from at least three licensed life insurers or an independent annuity-quote platform. SPIA payout rates vary materially by insurer, age, gender, joint options and COLA features—so market checks matter.
- Market yields: Check the U.S. Treasury daily yields (Federal Reserve H.15) and corporate bond curves; these are the inputs insurers use to back guarantees and signal broad pricing direction.
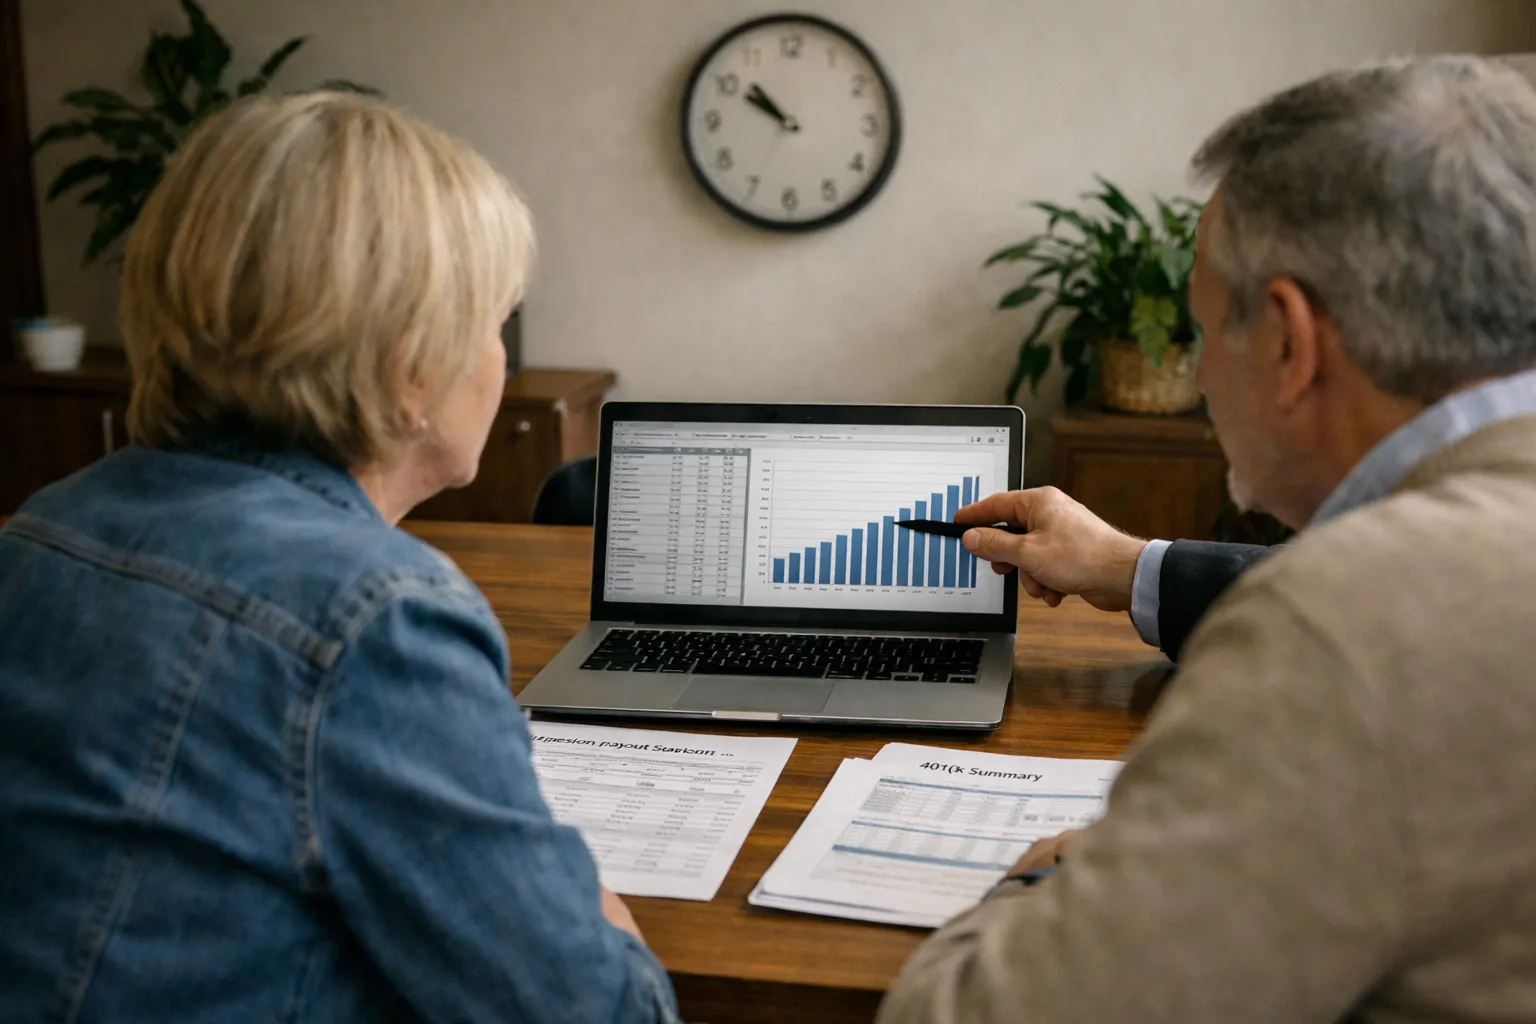
- Plan-specific terms: Request a formal pension options statement from your plan administrator specifying the pre-tax lump-sum, the detailed annuity options (single-life, joint options, any guaranteed period, COLA), and whether an in-plan annuity window is available.
Illustrative current-market context (August 2026): many 65-year-old single-life SPIAs are quoting higher payout factors than the low-rate era, sometimes in a mid-single-digit effective yield on the premium—this narrows, but does not eliminate, important differences with portfolio-based withdrawals once taxes, fees and longevity risk are considered.
Multiple perspectives: trade-offs from different stakeholders
Security-first retirees: Annuities remain the simplest way to remove longevity risk. A guaranteed floor streamlines budgeting for housing, healthcare and insurance costs—useful when you prioritize stable cash flow over leaving a large bequest.
Legacy-focused households: Lump sums rolled to an IRA (or converted to Roth strategically) preserve bequest value and control. Beneficiaries can inherit assets that may grow tax-advantaged under existing distribution rules, though SECURE Act distribution rules mean beneficiaries’ time horizons are constrained—so estate planning is essential.
Couples and survivor planning: Joint-and-survivor annuities reduce initial income but eliminate both spouses’ longevity risk. Alternatively, partial annuitization (enough to cover essentials) plus invested assets for discretionary spending and legacy may better balance survivor needs and estate goals.
Tax and benefits advisers: CPAs and fee-only planners emphasize that RMD timing at 73, Medicare IRMAA thresholds, and the interplay with Social Security taxation can change the after-tax attractiveness of either pathway—especially for high‑net‑worth retirees where marginal tax brackets and IRMAA penalties can be triggered by withdrawals or Roth conversions.
Updated illustrative example (August 2026)
Scenario: 65-year-old retiree chooses between a lifetime pension paying $38,000/year (single-life, no COLA) or a pre-tax lump sum of $630,000. How to compare today:
- Option A — Pension: $38,000 annually (ordinary income). No direct estate value unless a survivor benefit is chosen.
- Option B — Lump sum: Roll $630,000 to a traditional IRA. Model diversified portfolio withdrawals using conservative nominal return scenarios (3%–5%) and plan RMDs from 73. Evaluate partial Roth conversions in low-income years to reduce future RMD pressure.
With the narrowed annuity/portfolio gap in 2026’s higher-yield environment, the guaranteed pension commonly outperforms a conservative withdrawal strategy for covering core spending if the retiree lives into their 90s. However, the lump sum often wins for shorter lifespans, when heirs are a priority, or if the investor expects above‑average portfolio returns and wants flexibility.
How to structure a rigorous comparison — updated checklist
- Get every number in writing: pension option statement, lump-sum amount, survivor/joint options, COLA language, and whether an in-plan annuity exists.
- Shop annuity quotes: obtain at least three SPIA quotes plus DIA quotes for ages 80–85. Compare both insurer financial strength (A.M. Best, S&P) and payout rates.
- Model after-tax cash flows: include RMDs starting at 73, Medicare IRMAA trigger points, Social Security taxation bands, and staged Roth conversion scenarios across a 10–15 year horizon.
- Stress-test longevity and market scenarios: run outcomes for death at 80, 90 and 95; include a high-return scenario (market outperformance) and a low-return scenario (sequence-of-returns risk).
- Consider hybrid solutions: lock a core floor (30%–60% of essentials) with an annuity, hold liquid assets for taxes and legacy, and use DIAs to add a low-cost longevity layer starting later in life.
Tax, Medicaid and Medicare implications that alter the math
Tax timing and means-tested benefits often swing the decision. Practical points for August 2026:
- RMDs at 73: Still the baseline rule—rollovers into traditional IRAs create required withdrawals that can push you into higher marginal brackets and Medicare IRMAA bands. Annuity payouts are ordinary income when received and can be structured to smooth tax exposure.
- Roth conversions: Remain powerful for reducing future RMD pressure and creating tax-free income for heirs. Stagger conversions to take advantage of lower-bracket windows, and avoid funding conversions from the same IRA dollars being converted when possible.
- Medicaid planning: Large lump sums can jeopardize Medicaid eligibility for long-term care. Some annuities are treated favorably in means-testing when structured under federal/state rules—coordinate with elder-law counsel before making irreversible moves.
Practical recommendations — what to do right now (August 2026)
- Request a formal pension option statement and obtain at least three insurer SPIA quotes for equivalent single and joint payouts.
- Run after-tax cash-flow models that include RMDs at 73, Medicare IRMAA thresholds and staged Roth conversions; use a fee-only planner and CPA for accuracy.
- Consider partial annuitization: secure a floor sufficient for essential spending and retain liquidity for taxes, home costs and legacy planning.
- If Medicaid is a concern, consult an elder-law attorney before converting lump sums or buying annuities that could affect eligibility.
- Document your survivor preferences and coordinate with estate documents—trusts, beneficiary designations and liquidity plans can avoid forced asset sales by heirs.
Outlook: what to watch next
Three policy and market developments will change the calculus going forward:
- Interest-rate direction: Moves in the Treasury curve will directly affect SPIA pricing—lower yields widen the attractiveness of lump-sum investing; higher yields favor annuities.
- Plan-sponsor adoption: Continued growth of in-plan guaranteed-income options will make partial annuitization simpler and cheaper for participants.
- Regulatory changes: Any future tax-code revisions to RMDs, Roth rules, or annuity tax treatment would materially alter optimal strategies—monitor IRS guidance and Congressional action.
Checklist: immediate next steps
- Request your written pension options and confirm whether an in-plan annuity window exists.
- Obtain and compare at least three SPIA quotes and one or two DIA quotes for longevity layering.
- Have a CPA and fee-only planner model after-tax cash flows with RMDs at 73 and Roth conversion scenarios.
- Decide if a hybrid approach (annuitize a core, invest the rest) fits your goals, and document survivor and estate plans.
Frequently asked questions
How do RMDs at age 73 affect the lump-sum vs annuity choice?
RMDs force taxable withdrawals from traditional IRAs beginning at 73, which can increase marginal tax rates and trigger Medicare IRMAA surcharges and higher taxation of Social Security benefits. Annuity payments are taxed as received and can smooth taxable income timing. Model both paths—including staged Roth conversions—before deciding.
Should I buy a joint-and-survivor annuity for spouse protection?
Joint-and-survivor annuities reduce initial payout but guarantee lifetime income for the surviving spouse. If your spouse lacks independent income or you prioritize eliminating longevity risk for two lives, a joint annuity is a straightforward solution. If leaving a bequest matters, consider partial annuitization and keep a liquid bucket for heirs.
Can I convert a lump sum to a Roth to avoid future RMDs?
Yes—Roth conversions remove future RMDs and create tax-free growth and distributions for heirs. Conversions generate taxable income in the conversion year, so stagger them into low-income years and coordinate with Social Security claiming to minimize IRMAA and marginal-tax effects.
What role should deferred income annuities (DIAs) play today?
DIAs starting at ages 80–85 remain an efficient, lower-cost way to buy longevity insurance. Use DIAs as a complement to an immediate annuity floor: immediate annuities cover near-term essentials while DIAs protect against very long lives at a lower up-front cost.
Who should I consult before choosing?
At minimum consult a fee-only financial planner to run multi-scenario modeling and a CPA for tax projections. If Medicaid, long-term care or complex estates are possible considerations, add an elder-law attorney or estate planner to the team.
Choosing between a lump sum and lifetime annuity is a portfolio-level decision that affects taxes, housing, health coverage and inheritance. In August 2026, the options are more varied and market pricing is more favorable to guaranteed income than in the low‑rate era, but the right choice depends on lifespan, survivor needs, tax sensitivity and legacy goals. Get live quotes, model after-tax cash flows, and build a plan that secures essentials while preserving flexibility and legacy capacity.